


Login
Get Instant Pricing On 23,000+ Aircraft

>
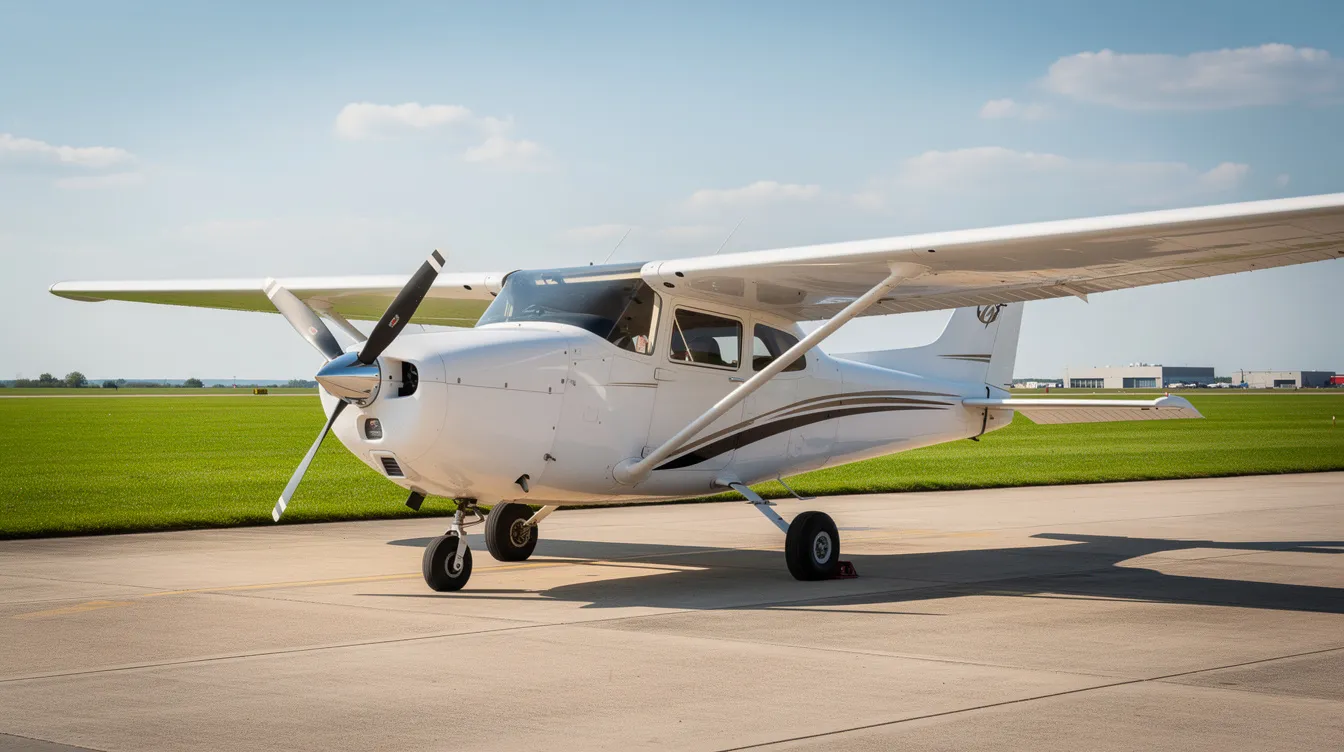
If you own or plan to buy a Cessna 172, insurance cost is one of the first fixed expenses you need to budget for. This guide breaks down what aircraft owners actually pay in 2026, the factors that drive premiums, and practical ways to keep costs manageable.
Cessna 172 insurance costs range from $150 to $1,400 annually for most private owner-pilots, depending on whether you carry liability only or add hull coverage. Typical Cessna 172 insurance premiums commonly range from about $1,200 to $5,000 per year when you factor in commercial or training use at the upper end. The Cessna 172 is one of the most affordable aircraft to insure, thanks to its massive fleet size and predictable risk profile.
Basic liability insurance for experienced pilots flying for personal pleasure typically runs $150 300 per year. Adding hull coverage brings the total into the $700 1,600 range for privately owned planes valued between $70,000 and $250,000. Insurance rates start at roughly 1% of the Cessna 172's hull value. Annual insurance costs vary based on pilot qualifications and use type — personal pleasure flying is generally cheaper to insure than commercial aviation operations.
A concrete example: a 1978 Cessna 172N valued at $90,000, flown 75 hours per year by a 500-hour pilot, can often be insured in the $900 1,200 annual range. For aircraft owners who only fly a few times per year, carrying fixed annual insurance may cost more per flight hour than simply chartering through an on-demand platform like Jettly, where coverage is built into the charter rate, especially when you consider affordable aeroplane rental costs and options.
The Cessna 172 is the most-produced airplane in history, with continuous production since 1955. Its wings, stable handling, and forgiving flight characteristics make it a staple across flight instruction, rentals, and private ownership worldwide.
Four seats, high-wing configuration, single piston engine (145 180 hp Lycoming)
Cruise speed around 110 125 knots, depending on model
Older models (1960s 1970s) typically valued at $60,000 120,000 in 2026
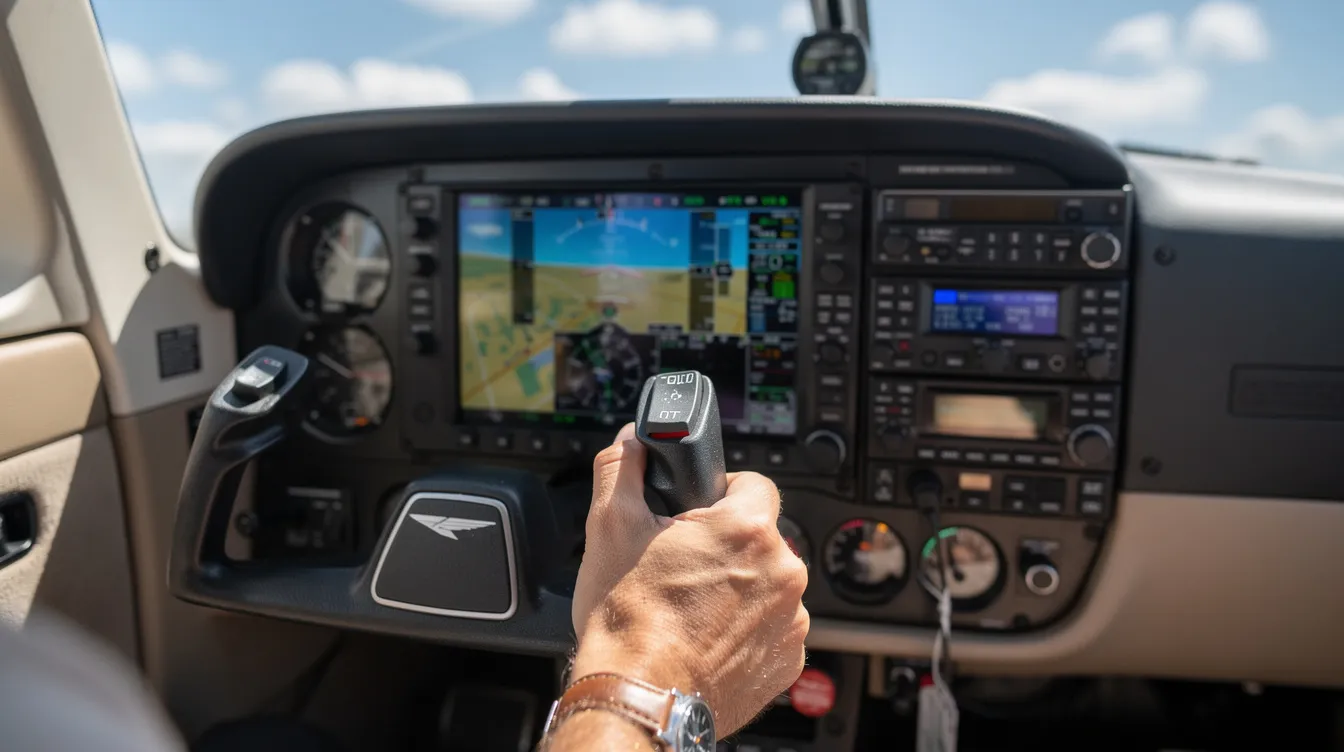
Late-model 2019 2026 Skyhawks with Garmin G1000 NXi are valued at $450,000 600,000
Older Cessna 172s cost less to insure due to lower hull value. Insurers favor this model because of its large global fleet, abundant parts supply, and strong safety history. Its prominence in aviation insurance portfolios — from flight schools to cross-country owner flights — means underwriters have deep data to price risk accurately, keeping premiums relatively predictable compared to higher-performance aircraft.
Insurance costs vary by pilot profile, aircraft age, and usage, but reliable ranges exist for most private Cessna 172 operations as of 2026.
|
Coverage Type |
Typical Annual Cost |
Notes |
|---|---|---|
|
Liability-only coverage |
$150 250 |
For experienced, non-commercial private pilots |
|
Hull coverage |
$500 1,200 |
Depends on agreed hull value |
|
Liability plus hull combined |
$700 1,600 |
For hull values between $70,000 and $250,000 |
|
Training or rental fleet |
$1,500 4,000+ |
Higher utilization and student exposure |
Two sample scenarios illustrate the broader principles covered in our comprehensive guide to airplane insurance costs:
Example 1: 1972 Cessna 172L, $75,000 hull, 300-hour private pilot, hangared in Texas - premiums around $850 1,050.
Example 2: 2018 Cessna 172S G1000 NXi, $480,000 hull, 1,200-hour instrument-rated owner, hangared in Florida - premiums often $3,800 to $ 4,600.
A useful rule of thumb: many aircraft owners pay around 1% of hull value per year for hull and liability combined. Newer pilots pay $850 to $1,400 for insurance premiums, while hull value increases premiums by approximately $1,000 per $100,000 of insured value. Insurance premiums increase with the aircraft's hull value, and commercial uses like flight schools, leaseback fleets, or fractional ownership of a Cessna 172 consistently fall at the higher end of the cost spectrum.
Aviation insurance underwriters evaluate both the aircraft and the pilot when pricing a policy. Factors influencing Cessna 172 insurance costs include hull value, pilot experience, and usage type. Here's how each breaks down:
Hull value and aircraft condition: Higher agreed hull values (e.g., $400k+ for a newer Skyhawk) directly increase the premium. Older, lower-value airframes cost less to insure but may face scrutiny for maintenance history and avionics age, which is important to weigh when evaluating budget-friendly aircraft ownership choices.
Pilot profile: Pilot experience is often the biggest cost driver for aircraft insurance. Accumulating 500 hours in a Cessna 172 lowers insurance costs significantly — underwriters see pilots with substantial time in type as a lower risk. First-year private pilots with under 100 hours typically face higher premiums because underwriters view them as a higher risk. Holding an instrument rating, completing recurrent training, and staying current on certificates and flight reviews can earn discounts of 3 10%.
Operational use: Personal and pleasure flying receives the lowest rates. Flight instruction, rental fleets, and commercial operations drive costs up because other pilots of varying skill levels increase exposure.
Storage and location: Hangar storage reduces hail, windstorm, and vandalism risk; tiedown storage is often treated as a higher risk, so hull premiums are usually higher than for hangared aircraft. Aircraft based in hurricane-prone regions like Florida or high-weather areas may carry surcharges compared to mid-country locations.
A clean claims history can help keep insurance rates low. Prior accidents or incidents linked to the pilot or aircraft can significantly increase future aviation insurance premiums for multiple renewal cycles, just as they do for larger aircraft when you evaluate the full cost of private jet ownership.
Cessna 172 insurance splits into liability and hull coverage types, with optional extras layered on top. Understanding what each component protects makes sense when evaluating quotes.
Liability coverage: Covers bodily injury and property damage to third parties per occurrence. Common limits: $1 million per occurrence with $100,000 per passenger sublimits, or smooth $1 million limits (no per-passenger cap). Higher limits are recommended for owners carrying family, friends, or business passengers.
Hull coverage: Protects the airplane itself against physical damage—both "in-motion" (flight, taxi) and "not-in-motion" (parked). Agreed value coverage pays the pre-determined aircraft value if totaled, avoiding depreciation disputes. Stated value coverage depreciates the aircraft's worth at loss time, which can leave an owner short after a total loss.
Common add-ons: Medical payments coverage is available for passengers on board. Physical damage coverage protects against ground incident damages like hangar rash, windstorm, or towing. Non-owned aircraft coverage is for pilots who also fly rental or club planes.
Be aware of exclusions: using a Cessna 172 for commercial passenger carriage when only private use is declared can void the policy entirely.
Protecting your plane and your money doesn't require overpaying at renewal. Here are concrete levers every owner should consider.
Complete FAA WINGS programs or instrument proficiency checks annually: This signals lower risk to underwriters.
Build time in type: Insurers often offer better terms once a pilot logs 25 50 hours specifically in the Cessna 172.
Raise your deductible: This lowers your premium, but only if you're comfortable covering higher out-of-pocket repair costs.
Set hull value to a realistic market number: Over-insuring means paying unnecessary money each year.
Modern avionics upgrades: Demonstrate a commitment to safety and may support better pricing with some insurers
Maintain clean logbooks: AD compliance, timely annual inspections, and complete maintenance records help your broker argue for favorable terms and lower insurance premiums.
Shop around for different insurance quotes: Use an aviation-specific broker and leverage what you learn from a comprehensive guide to airplane insurance costs for the best rates.
Renew early and provide complete pilot and maintenance data: This helps avoid last-minute surcharges.
For very low annual utilization (under 30 40 hours per year), some pilots find it makes sense to fly less and charter more through services like Jettly, especially when private jet memberships provide flexible access without long-term commitments, avoiding the tie-up of capital in fixed insurance and ownership costs.
The Cessna 172 carries a strong safety reputation across the country, which helps keep its aircraft insurance costs moderate and makes it a useful point of comparison against the broader landscape of private and charter airlines.
Heavy use in flight schools with student pilots leads to frequent hard landings and minor incidents, but the 172's forgiving stall characteristics and high-wing visibility contribute to relatively low severe accident rates compared to more complex aircraft. Insurers often view the Cessna 172 as a profitable risk category, which supports competitive premiums across the market.
Regarding pilot age: some underwriters begin scrutinizing pilots once they have passed 70, with more restrictive terms often appearing around ages 75 80. Consistent flying, current ratings, and medical fitness help older pilots maintain affordable coverage. Newer Skyhawks equipped with G1000 NXi, synthetic vision, and autopilot further improve the safety data profile, especially in IMC.
Owning a Cessna 172 means buying into fixed annual costs regardless of how many hours you fly. Combine $1,000 1,500 in annual insurance with hangar fees, maintenance reserves, and fuel, and the break-even point for ownership versus chartering shifts quickly for low-utilization pilots.
Charter clients don't pay separate aircraft insurance — coverage is embedded in the operator's prices. For travelers who primarily need point-to-point convenience for business or family trips, chartering a small plane through Jettly can be more cost-effective than owning and insuring a personal airplane, especially once you understand how much it costs to rent a private jet.
A pilot who flies locally for leisure may still prefer ownership. But a business traveler flying longer regional routes may save time and money by booking a turboprop or light jet on demand instead of maintaining a personal 172. Jettly offers access to a large global aircraft inventory with transparent, upfront pricing through its comprehensive private aviation platform — no log of annual insurance bills, no hangar contracts, and no maintenance surprises.
Insurance costs for a Cessna 172 generally range from $150 to $1,400 annually for private pilots, depending on coverage type and pilot experience. Commercial or training uses can increase premiums to $1,500 to $5,000.
The biggest factors include the aircraft's hull value, pilot experience and total hours, usage type (personal vs. commercial), and storage location. Newer pilots and commercial operations usually face higher rates.
Yes. Pilots with 500+ hours in the Cessna 172 and additional ratings like instrument proficiency typically pay significantly less than new pilots with under 100 hours.
Coverage typically includes liability insurance, hull coverage (agreed or stated value), medical payments for passengers, and physical damage protection for ground incidents.
Yes. Maintaining a strong pilot profile with recurrent training, raising deductibles, storing the aircraft in a hangar, upgrading avionics, and shopping multiple quotes through aviation-specific brokers can help lower premiums.
For low-utilization pilots, chartering through platforms like Jettly can be more affordable since insurance and maintenance costs are embedded in the charter rate, avoiding fixed annual expenses.
Learn more about Jettly’s charter options at https://www.jettly.com
Most Cessna 172 aircraft owners can expect insurance costs to land around 1% of hull value annually, with low-time pilots, commercial use, and newer airframes pushing premiums higher. Understanding key rating factors — pilot hours, hull value, storage, and usage — gives owners real leverage to keep aviation insurance affordable without sacrificing coverage, whether they eventually transition into private charter aircraft or remain in single-engine ownership.
The Cessna 172's favorable safety record and widespread use keep the insurance market competitive for this model. For those who decide that owning, maintaining, and insuring a plane no longer fits their lifestyle, on-demand charter remains a flexible alternative, and platforms that offer affordable private jet charter can make that shift financially attractive.
Ready to explore private travel on your terms? Discover instant pricing, flexible booking, and access to thousands of aircraft at jettly.com; compare it as a flexible NetJets alternative, or lock in consistent rates through corporate jet card programs
Share this post:
Jeff Ryan Serevilla
Sep 22, 2026
|
5
min read
Discover tips and trends in the industry.
5
min read
Cleveland Jet Charter: Private Flights to and from Cleveland, Ohio
Cleveland Jet Charter offers travelers the flexibility and convenience of private flights to and from Cleveland, Ohio. With access to over 20,000 aircraft globally, Jettly simplifies the booking process, allowing clients to choose their departure times and aircraft without long-term commitments. Ideal for business or leisure travel, private jet charters provide enhanced privacy and productivity.
Read More
5
min read
What's a Transatlantic Flight? (History, Routes, Private Jets & Planning)
A transatlantic flight is any air journey that crosses the Atlantic Ocean, connecting continents like North America and Europe. This guide explores the history, modern routes, and private jet options for transatlantic travel, highlighting the evolution from early flights to today's efficient services. Jettly offers insights into planning and booking private transatlantic flights, ensuring flexibility and comfort for travelers.
Read MoreStay updated with our latest insights and tips to elevate your journey with us.
MEMBERSHIPS AND ASSOCIATIONS


Disclaimer: Jettly operates as a charter broker, offering access to a global digital jet charter marketplace. Jettly is not a direct air carrier and does not own or operate aircraft. All advertised flights are conducted by third-party air carriers that are fully licensed and hold the appropriate Part 135 or Part 121 certifications issued by the Federal Aviation Administration (FAA) or equivalent regulatory authorities under U.S. or foreign law. Jettly complies fully with the U.S. Department of Transportation's Part 295 and Part 298 Charter Broker regulations. Jettly does not carry additional liability insurance. Passengers are covered by aircraft operator insurance. TICO: 50023770


