


Login
Get Instant Pricing On 23,000+ Aircraft

>
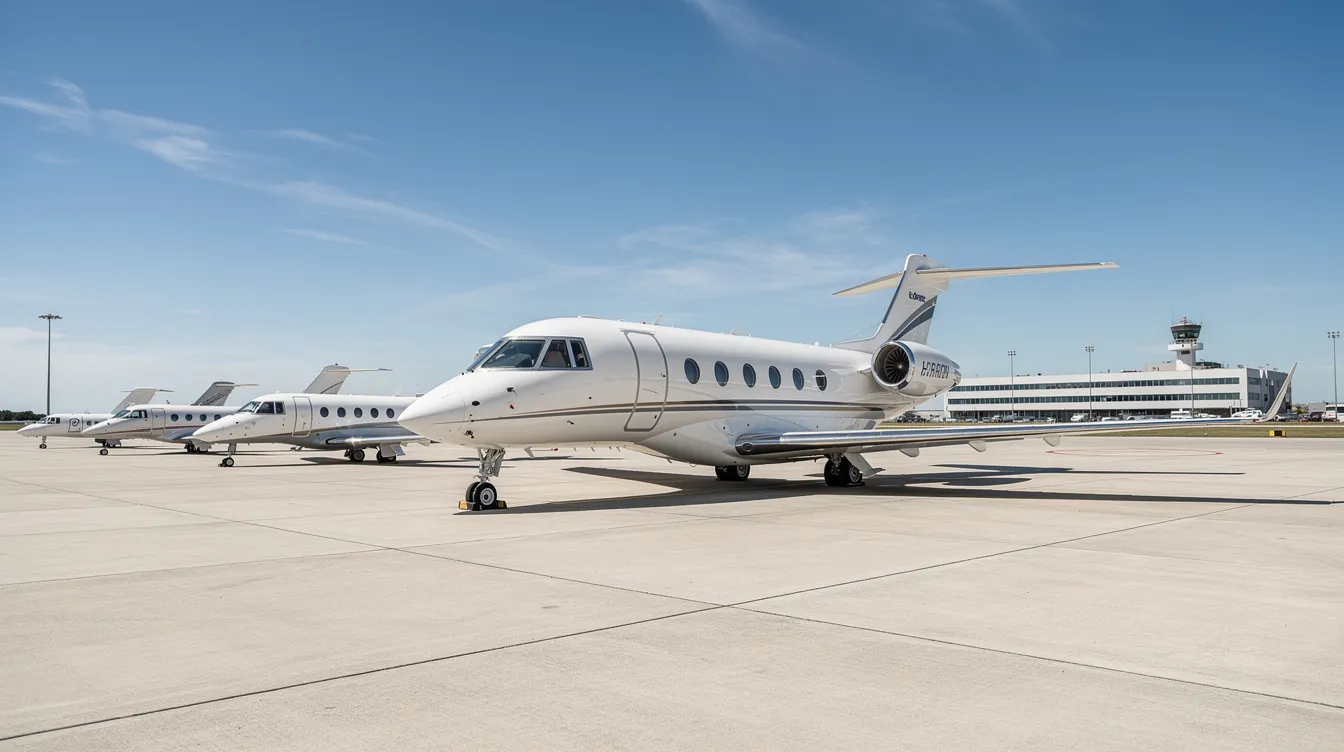
The jet market spans commercial airliners, business jets, and private aircraft of all sizes. Business jets are aircraft designed for transporting small groups of people, typically for corporate or private use. Private jets refer to business jets that are owned or chartered for non-commercial, personal, or business travel. This article focuses on the private jet market, where the active global business jet fleet is approaching 24,900 aircraft and demand continues to climb. The private jet market is expected to grow from USD 25.5 billion in 2024 to USD 38.25 billion by 2033, driven by business travel, rising wealth, and new technology in airframe and engine design.
Jettly operates as a digital private aviation platform that connects travelers with on-demand charter flights across a network of over 20,000 private charter aircraft. Instead of buying or leasing a jet, users book flights trip by trip, with instant pricing and transparent cost breakdowns. Private jet buyers value convenience, flexibility, and privacy in travel; Jettly's model is built around those priorities.
This article is intended for business travelers, aviation professionals, and anyone interested in understanding the current trends, growth drivers, and opportunities in the global private jet market.
Time savings: private aircraft access smaller airports closer to final destinations, cutting ground transit
Schedule flexibility: flights depart on the traveler's timeline, not the airline's
Regional connectivity: charter fills gaps where commercial routes are indirect or nonexistent
Health and safety: post-pandemic travelers continue to prefer controlled cabin environments
The global business and private jet market is valued at approximately $50.60 billion to $83.97 billion depending on scope. The global business jet market revenue alone is estimated at over $83 billion in 2026, according to industry analyses. The private aircraft market is projected to reach USD 50.8 billion by 2034, growing at a CAGR of 6.7% from 2025 to 2034.
Business jets account for over 34% of the private aircraft market share, while the light aircraft segment captured more than 40% of the market in 2024. The corporate market segment holds over 38% market share in 2024, reflecting strong demand from companies that need regular access to business aircraft.
North America holds over 45% of the private aircraft market share in 2024, supported by the world’s largest installed fleet of private jets. Europe ranks second by revenue. Asia Pacific is the fastest-growing region by fleet additions, with emerging markets in the Middle East also contributing to market expansion. Economic conditions influence the market for both commercial and business aircraft; interest rates, corporate profitability, and currency fluctuations all affect acquisition and charter demand across regions.
A regional comparison of approximate 2024 vs. projected 2033 market contributions: North America is the leading regional market with the largest installed fleet and revenue base. Europe follows, shaped by sustainability regulation. Asia Pacific shows rapid growth in new deliveries and fleet count. The Middle East drives demand through infrastructure investment and tourism.
The private aircraft industry breaks into several segments: new vs. pre-owned aircraft, charter vs. ownership, and aircraft size classes ranging from light jets to ultra-long-range jets. For prospective buyers, understanding how much a private jet costs across sizes and ownership models is central to deciding which segment fits their budget and mission. Pre-owned business jet inventory remains below historical averages at around 6.5% of the active fleet, limiting the number of aircraft listed for sale in the pre-owned market. With fewer aircraft sold, resale prices remain firm and push some buyers toward charter.
Large-cabin and ultra-long-range business jets capture the largest share of market value per unit. Large business jets are expected to dominate market share in the post-pandemic period, as corporations and high-net-worth individuals prioritize nonstop intercontinental range, often choosing among leading private and charter airlines that specialize in these mission profiles.
|
Category |
Passengers |
Range (nm) |
Examples |
|---|---|---|---|
|
Light jets |
5-7 |
~2,000 |
Citation CJ3+, Phenom 300E |
|
Midsize |
7-9 |
~3,000 |
Hawker 900, Citation XLS+ |
|
Super-midsize |
8-10 |
~4,000 |
Challenger 350, Gulfstream G280 |
|
Large business jet |
10-14 |
~6,000 |
Gulfstream G550, Falcon 900 |
|
Ultra-long-range |
12-18+ |
7,000+ |
Global 7500, Gulfstream G700 |
Common use cases include short-haul business trips between secondary cities, transcontinental executive travel, family vacations to airports without commercial service, and urgent medical or corporate missions. Tools such as Jettly’s airport locator for secondary and private airports help travelers identify suitable departure and arrival points, while a comparison of private jet types helps match aircraft to mission. Jettly's marketplace allows users to filter by jet aircraft class and passenger count, accessing different segments of the market without ownership.
One of the primary growth drivers behind rising private jet demand is the increasing number of high-net-worth individuals worldwide. As personal wealth concentrates, more travelers can afford charter or fractional access, adding pressure to the expanding global fleet of private jets. Fleet replacements are also fueling new acquisitions in the business jet market, as older aircraft cycle out and operators upgrade to newer, more fuel-efficient models.
The COVID-19 period (2020-2022) reset traveler expectations around personal space and health security. Many first-time users entered the private jet market during that window. Private jet inventory increased by 48% to 67% in 2023 as the pre-owned market expanded. The G550 market alone saw a 500% increase in inventory. Average time on the market for jets is now 260 days, up from pre-pandemic levels, reflecting a shift from the acute demand spike of 2021-2022 toward a more balanced supply-demand environment.
Rising demand for charter and membership models, including platforms like Jettly, reduces barriers compared with outright ownership. Travelers who need same-day private jet charter, want to crowdsource private jet flights and share empty seats, or access empty leg flights can book without long-term commitments.
One example of why travelers choose private jets:
Same-day multi-city roadshows across three or four stops in a single business day
Board meetings in secondary cities where commercial flights require overnight stays
Last-minute family trips to resort destinations served only by small airports
Medical evacuations or urgent cargo requiring specialized aircraft on short notice
Sports teams and touring groups traveling as small groups with heavy equipment
North America secured over 45% share of the private aircraft market in 2024 and remains the largest market by registrations, deliveries, and charter activity. A dense network of over 5,000 public-use airports makes private aviation practical for both business travel and leisure. The American jet charter guide covers common routes and pricing.
Europe maintains strong demand on routes like London-Geneva and Paris-Nice. Sustainability regulation is tightening; several EU member states are advancing mandates for sustainable aviation fuels blending. Charter operators in Europe increasingly price SAF surcharges into quotes.
Asia Pacific is the fastest-growing region. The fleet reached 1,168 business jets by the end of 2025, up 1.5% year-on-year. India added 20 aircraft to reach 188, making it the third-largest market in the region and supporting demand for private jet charter in Kolkata and other Indian gateways. Southeast Asia posted 6.2% fleet growth. South Korea, with its export-driven economy and dense tech sector, shows growing interest in intra-Asia charter for executives connecting Seoul to regional hubs across the continent.
Regional demand snapshot, including growing charter activity around New Delhi and other Indian hubs:
North America: highest charter utilization; strong demand from corporate and leisure segments
Europe: mature market; environmental awareness shaping buyer and charter operator behavior
Asia Pacific: rapid growth in India, Southeast Asia; rising demand for intercontinental missions
Middle East: infrastructure investment and tourism drive demand; clients favor long-range aircraft
Latin America: smaller but growing; political and economic volatility creates uneven demand
Technological advancements are expected to improve aircraft performance and fuel efficiency across the aviation sector. Environmental regulations are forcing manufacturers, including Dassault Aviation, Textron Aviation, Bombardier Inc., and Cirrus Design Corporation, to prioritize fuel-efficient aircraft designs and propulsion development in current and next-generation programs.
On the aircraft side:
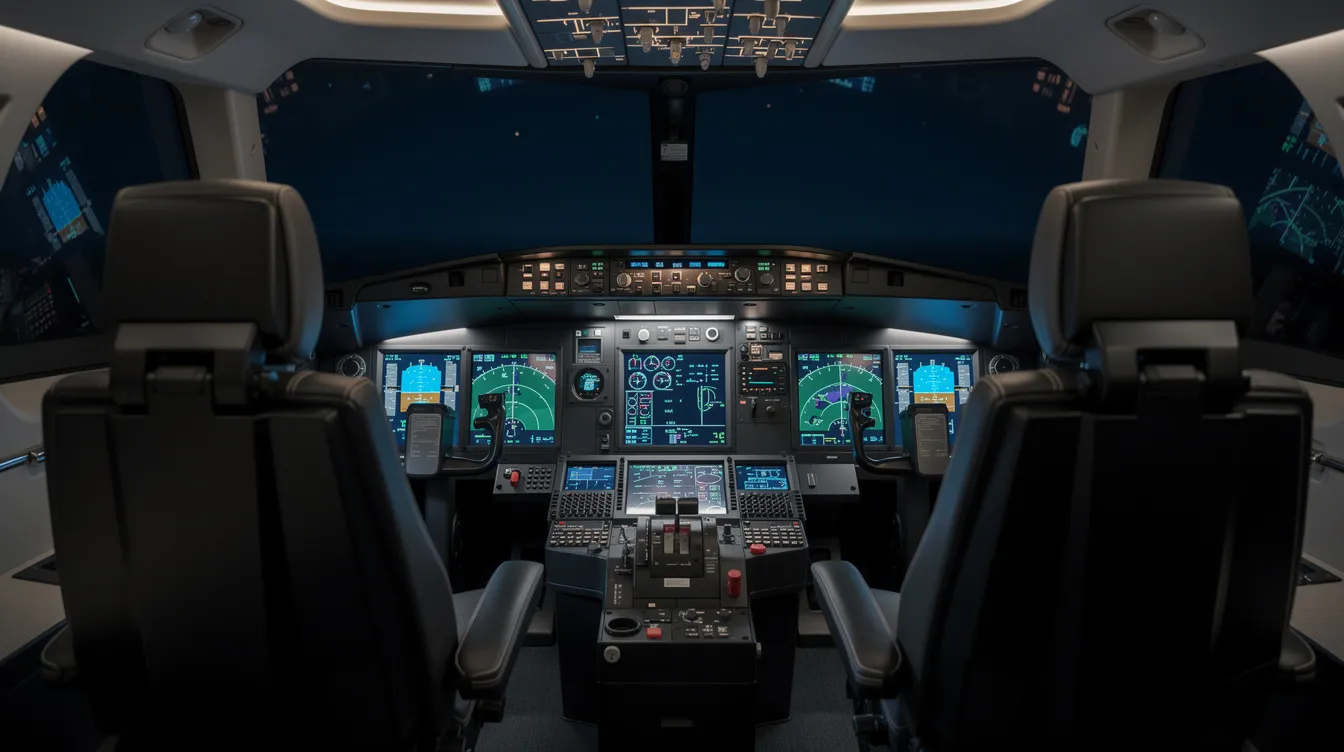
Digital cockpit systems improve aircraft performance and cost savings; full glass cockpits on newer Gulfstream and Bombardier models allow real-time engine and systems monitoring
AI integration enhances operational efficiency in private aviation, from predictive maintenance to fuel burn optimization; one study found predictive maintenance reduced unscheduled events by 35-40%
Hybrid electric propulsion reduces emissions and fuel consumption; several manufacturers have prototype programs in testing
Lightweight composites, winglets, and aerodynamic refinements cut drag and operating costs
On the digital platform and charter side:
Instant pricing and automated quoting tools let travelers compare aircraft and costs in minutes
Big data and route optimization reduce empty positioning legs for charter operators, improving charter operations
Integrated ground transportation and in-flight catering options through Jettly Eats simplify door-to-door travel planning.g
The commercial aircraft order backlog reached approximately 18,100 aircraft in May 2026. Heavy backlogs are altering how pricing power and delivery schedules are managed in aircraft production, pushing wait times for new business jets to two or three years for popular models. Geopolitical instability affects airlines' fuel prices and profitability, which in turn influences fleet planning and charter pricing.
Pilot and maintenance engineer shortages remain a constraint. Training pipelines for certified jet pilots take 18-24 months at minimum, and retention is difficult when demand from commercial airlines competes for the same talent pool. Investment in aircraft maintenance, repairs, and parts is expected to grow due to increased demand for older aircraft still in active service.
Regulatory timelines for certifying new technologies, including SAF blending ratios and noise-reduction systems, add cost and delay to aircraft programs. These factors tighten charter availability and push rates upward when operators face maintenance backlogs or crew shortages.
How flexible charter helps navigate these constraints:
Platforms like Jettly tap a global network of operators, absorbing local supply shortages
Users avoid the capital outlay and depreciation risk tied to ownership
On-demand access means travelers are not locked into a single aircraft or operator when market conditions shift
Owning a private jet can cost millions annually. Fixed expenses include crew salaries, insurance, hangar fees, and scheduled maintenance. Private jet operating costs span both fixed and variable categories, and maintenance costs for private jets can be unexpectedly high, especially on aging airframes, as outlined in dedicated guides to private jet maintenance expenses. Crew salaries and insurance add to ownership expenses, and hangar fees contribute to operational costs at busy airports. High operational costs limit private jet ownership to wealthy individuals who fly 200+ hours per year, and they also make charter more attractive for travelers considering a small jet for occasional use. A detailed breakdown is available in Jettly's private jet charter costs guide.
Fractional jet ownership and more structured fractional jet ownership programs with defined pros and cons, along with jet card programs offering fixed hourly rates, opened the market to more users, but both require medium- to long-term commitments and predictable flying patterns. On-demand charter, by contrast, carries no fixed costs.
When to choose each model:
|
Access Model |
Best For |
Annual Hours |
Commitment |
|---|---|---|---|
|
On-demand charter (Jettly) |
Occasional flyers, variable schedules |
Under 50 |
None |
|
Regular travelers wanting rate guarantees |
25-100 |
Low |
|
|
Fractional ownership |
Predictable schedules, single aircraft preference |
100-200 |
Medium |
Emerging markets in Asia Pacific, the Middle East, and parts of Latin America will shape future growth. India's fleet expansion, Southeast Asia's 6.2% growth rate, and Middle East infrastructure investment all point to continued market expansion. Strategic partnerships between regional operators and global platforms are expected to accelerate access in these regions.
Public scrutiny around private jet emissions is real. Research from the ICCT found a typical private jet emits about 810 tonnes of GHGs annually, equivalent to emissions from 177 average cars. Operators are increasingly adopting sustainable aviation fuel to address environmental scrutiny. SAF can reduce lifecycle greenhouse gas emissions, and several manufacturers are testing sustainable aviation fuel compatibility across their fleets. For travelers evaluating options, understanding how renting a plane works, including safety and operational considerations, is increasingly tied to questions about efficiency and environmental impact. Innovations in sustainable aviation, combined with operational efficiency gains and carbon offset programs, form the industry's near-term response.
Looking toward 2033-2034, the private jet market is on track for continued expansion. Charter demand is expected to grow faster than ownership, driven by first-time users and buyers who prefer variable costs over fixed capital commitments. Greater digitalization of booking, fleet management, and aircraft comparison tools will make the competitive landscape more transparent. Recent developments in data-driven matching between travelers and aircraft types will define the next phase of this strong market.
Jettly aggregates a global inventory of private aircraft and business jets, from light jets for short regional hops to large business jet options for intercontinental flights. Positioned as a flexible NetJets alternative focused on on-demand charter and memberships, the platform's core features include instant pricing via the charter cost estimator, digital booking, safety-vetted operators, and flexible membership options.
For frequent business travelers and families alike, Jettly offers access to smaller airports, integrated catering, and ground transportation coordination. Travelers who prefer to pay per seat can also explore how to buy a seat on a private jet through shared and semi-private options. Learn how to book a private jet through the platform in minutes.
The private jet market is projected to keep expanding through the forecast period, shaped by rising demand, new technology, and broader access models. As access broadens and more travelers learn how to get a seat on a private jet easily via memberships, apps, and flight-sharing platforms, affiliate partners can also participate in this growth through Jettly’s ULTRAhigh-ticket affiliate program. Ready to explore the private jet market on your terms? Learn more about Jettly's charter options or request a quote at https://www.jettly.com.
Share this post:
Jeff Ryan Serevilla
Oct 9, 2026
|
5
min read
Discover tips and trends in the industry.
5
min read
Private Jet Demand: How the Market Evolved, Who's Flying, and What It Means for Charter in 2026–2030
The private jet market has seen a significant surge in demand, remaining 35% above pre-pandemic levels through mid-2026. This trend is driven by a broader demographic of first-time flyers, increased flexibility, and the rise of digital booking platforms. As the industry evolves, travelers can expect tighter availability and a focus on sustainability through 2030.
Read More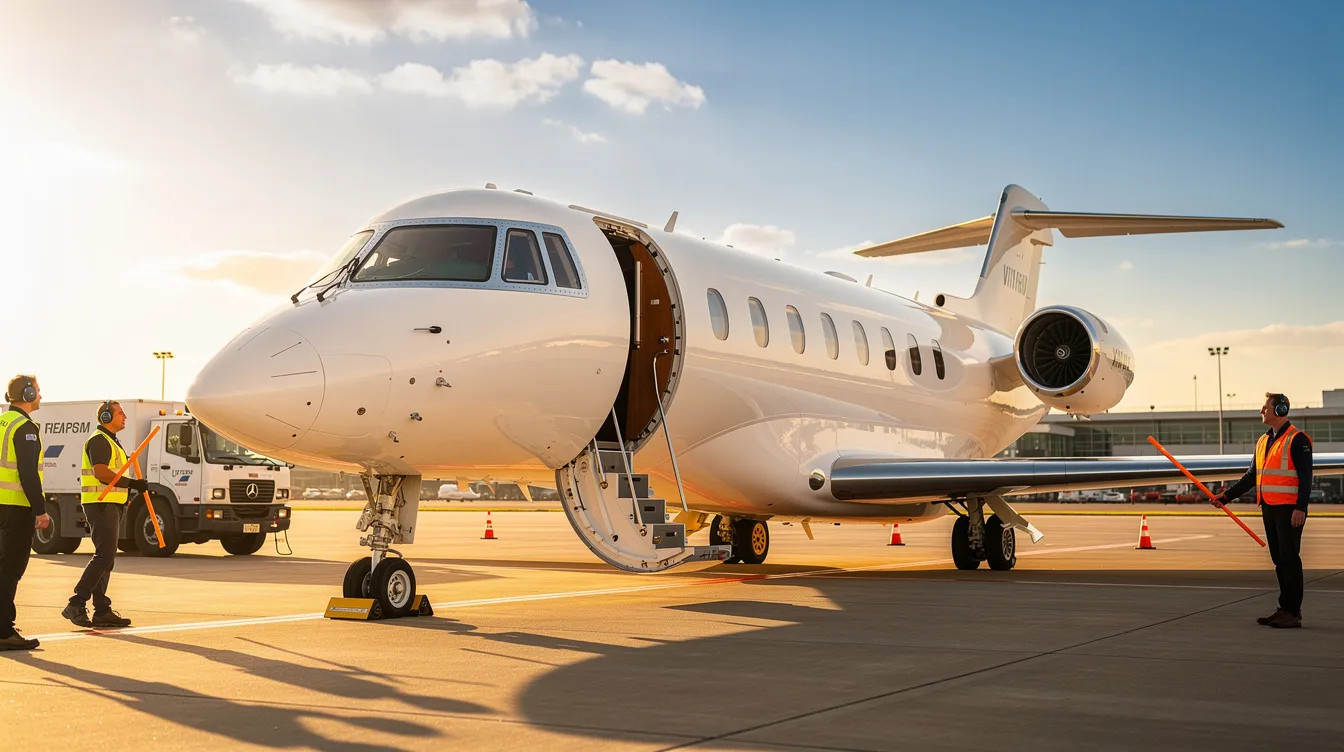
5
min read
Private Flight Club Membership Cost: What You Really Pay For
Private flight club memberships offer a range of costs influenced by initiation fees, monthly dues, and hourly rates. Understanding these components helps travelers make informed decisions between membership and on-demand charter options. With costs varying significantly based on aircraft type and usage, it's essential to evaluate personal travel needs and frequency before committing.
Read MoreStay updated with our latest insights and tips to elevate your journey with us.
MEMBERSHIPS AND ASSOCIATIONS


Disclaimer: Jettly operates as a charter broker, offering access to a global digital jet charter marketplace. Jettly is not a direct air carrier and does not own or operate aircraft. All advertised flights are conducted by third-party air carriers that are fully licensed and hold the appropriate Part 135 or Part 121 certifications issued by the Federal Aviation Administration (FAA) or equivalent regulatory authorities under U.S. or foreign law. Jettly complies fully with the U.S. Department of Transportation's Part 295 and Part 298 Charter Broker regulations. Jettly does not carry additional liability insurance. Passengers are covered by aircraft operator insurance. TICO: 50023770


